The November 3, 2026, midterm elections have shifted the balance of power in Washington, with Democrats winning control of both the House and the Senate in a major setback for President Donald Trump’s legislative agenda. The result could influence debates over federal income tax rates, deductions, family tax credits, and business tax policies as the new Congress prepares to take office on January 3, 2027. However, an election result does not automatically rewrite the tax code. Existing tax laws remain in effect unless lawmakers pass new legislation and it becomes law. For taxpayers, families, and business owners, the important question is not whether their tax bills will change overnight, but which provisions could come under review and how personal and business tax planning can help them prepare for potential changes. The 2026 midterm results mark an important shift in the political landscape that could shape future tax discussions.
Democrats Take Control: Is Trump's Tax Agenda Now at Risk?
Democrats’ victories give the party control of both chambers of Congress and greater influence over the legislative agenda, committee leadership, and congressional oversight. That could put parts of the 2025 tax law, including provisions affecting workers, families, and businesses, under renewed scrutiny.
Democratic lawmakers may propose changes to tax rates, deductions, credits, or business incentives. But President Trump remains in office and can veto legislation, while Senate rules may make some proposals difficult to pass. Major tax changes could require negotiation, bipartisan support, or a strategy that qualifies for budget reconciliation.
For now, the 2025 tax law remains in place. A proposal is not a repeal. The Congressional Research Service’s overview of Public Law 119-21 explains the tax provisions enacted under that law.
Will Your Personal Income Taxes Change After Trump's Midterm Defeat?
The new congressional majority could reopen discussions about personal tax policy. However, current federal rates, deductions, and credits do not change automatically after an election. Here’s what taxpayers should understand and monitor.
Could Federal Income Tax Rates Change?
Democrats may propose changes to federal income tax brackets, particularly for higher-income households. For the 2026 tax year, the federal marginal income tax rates remain 10%, 12%, 22%, 24%, 32%, 35%, and 37%. Each rate applies to a portion of taxable income, and the brackets vary by filing status. See the IRS 2026 tax inflation adjustments for the applicable thresholds.
What Could Happen to Tax Deductions and Credits?
Deductions reduce taxable income, while credits directly reduce the tax owed. Key 2026 provisions include:
- Standard deduction: $16,100 for single filers, $32,200 for married couples filing jointly, and $24,150 for heads of household.
- State and local tax (SALT) deduction: The federal limit is generally $40,400, or $20,200 for married taxpayers filing separately. For 2026, the limit begins to phase down when modified adjusted gross income exceeds $505,000, or $252,500 for married taxpayers filing separately. The deduction cannot be reduced below $10,000, or $5,000 for married taxpayers filing separately.
- Child Tax Credit: Eligible families may claim up to $2,200 per qualifying child, subject to income limits and other requirements.
Future proposals could affect these provisions, but taxpayers should use the current rules when preparing their returns. See IRS guidance on deductible taxes, the 2026 tax changes, and the Child Tax Credit.
Are Overtime, Tips, and Senior Tax Deductions at Risk?
The 2025 tax law introduced deductions for certain workers and older taxpayers. They are currently scheduled to apply for tax years 2025 through 2028, subject to eligibility and income limits.
- Qualified overtime deduction: Up to $12,500, or $25,000 for joint filers. It generally applies to the overtime premium required under the Fair Labor Standards Act, such as the extra half of time-and-a-half pay, rather than the employee’s entire overtime payment.
- Qualified tips deduction: Up to $25,000 for eligible workers in occupations that regularly receive tips.
- Additional senior deduction: Up to $6,000 per eligible taxpayer aged 65 or older, subject to income-based phaseouts.
These are federal income tax deductions, not blanket exemptions from income or payroll taxes. Review the IRS guidance on deductions for workers and seniors and qualified overtime compensation.
What Should Personal Taxpayers Expect?
Review your income, filing status, withholding, and eligibility for deductions and credits. Keep records of qualifying overtime, tips, dependent expenses, and other relevant items. If lawmakers propose changes, check whether they become law and when they take effect.
Which Taxpayers Should Pay Attention to Potential Tax Changes?
Taxpayer situation | Tax provision to review | Why it matters |
Employees earning overtime | Qualified overtime deduction | Only qualifying overtime premium counts toward the federal deduction. |
Workers receiving tips | Qualified tips deduction | Eligible workers may deduct qualifying tips under federal rules. |
Families with children | Child Tax Credit | Changes could affect the credit amount or eligibility. |
Homeowners and itemizers | SALT deduction | The federal limit and income-based reduction may affect itemized deductions. |
Eligible seniors aged 65+ | Additional senior deduction | Qualifying taxpayers may claim an additional federal deduction. |
The takeaway: Current federal tax benefits remain available under existing eligibility rules until the law changes.
Small Businesses Could Face a Different Tax Landscape. Here's What to Watch
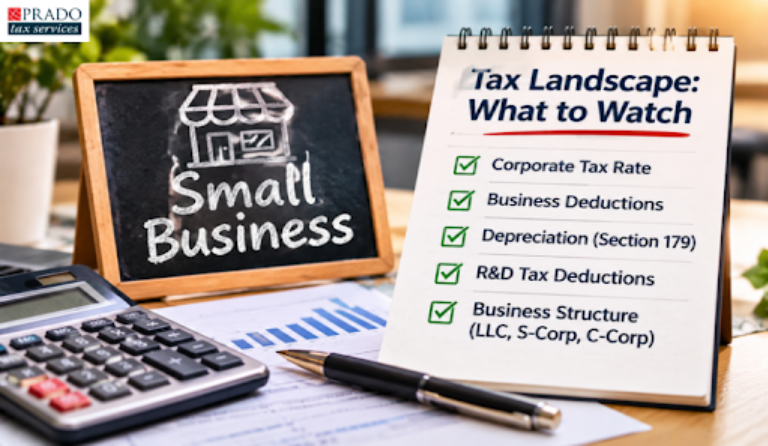
Business owners should monitor possible changes involving corporate tax rates, pass-through income, depreciation, and research expenses. These rules can affect taxable income, investment timing, and cash flow, but the impact depends on the business’s structure and activities.
Could Corporate Tax Policies Become a Political Battleground?
The federal corporate income tax rate for C-Corporations is currently 21%. Democrats could propose changes, but any revision would require legislation. Many small businesses are pass-through entities, meaning business income generally flows to owners’ personal tax returns rather than being taxed at the corporate level.
Will Business Deductions and Bonus Depreciation Change?
The 2025 tax law provides a permanent 100% additional first-year depreciation deduction for qualifying property acquired and placed in service after January 19, 2025, subject to the rules. For tax years beginning in 2026, the maximum Section 179 deduction is $2.56 million and begins to phase out when qualifying property placed in service exceeds $4.09 million.
These provisions may allow a business to deduct qualifying equipment costs sooner. The purchase date, placed-in-service date, property type, and business circumstances matter.
For example: Suppose a business purchases $100,000 of qualifying machinery and places it in service during 2026. If the machinery meets the requirements for 100% bonus depreciation, the business may be able to deduct the full eligible cost in the year it is placed in service. This could reduce its federal taxable income for that year. The actual tax benefit depends on the business’s eligibility, taxable income, and other applicable rules.
Could Changes to R&D Tax Deductions Affect Businesses?
Under Section 174A, eligible domestic research or experimental expenses can generally be deducted in the year paid or incurred. Foreign research expenses generally remain subject to 15-year amortization. These rules may affect businesses investing in software, technology, products, or process development.
Could LLCs, S-Corps, and C-Corps Be Affected Differently?
- LLCs: A single-member LLC is generally treated as a disregarded entity by default, while a multi-member LLC is generally treated as a partnership. An eligible LLC may elect corporate tax treatment.
- S-Corps: Generally pass income, deductions, and credits through to shareholders. Shareholder-employees must also follow payroll and reasonable-compensation rules.
- C-Corps: Pay corporate income tax on taxable profits. Shareholders may also owe tax when profits are distributed as dividends.
A change to corporate rates, pass-through deductions, or business expense rules could affect these structures differently. Business owners should review their entity classification and tax strategy before making structural changes.
The takeaway: Monitor proposed changes while reviewing current deductions, investment plans, bookkeeping, and business structure. The right approach depends on the company’s operations and tax position.
Why Your Taxes Won't Change Overnight: Understanding the Legislative Process
Even when one party controls both chambers of Congress, changing federal tax law takes more than announcing a proposal. A bill generally must pass the House and Senate in the same form before going to the president, who can sign it or veto it. Congress can override a veto only with a two-thirds vote in each chamber.
The Senate filibuster can also affect the process. Many bills need 60 votes to move past a filibuster. Certain qualifying tax and budget measures may use budget reconciliation, which can allow passage by a simple majority but comes with procedural limits.
Keep these stages in mind:
- Proposed: A lawmaker has announced an idea or introduced a bill. The tax code has not changed.
- Passed: Congress has approved legislation, but presidential action may still be required.
- Enacted: The legislation has become law. Its effective-date provisions determine when it applies.
A proposal announced in 2027 may not affect a 2026 tax return. Follow the Congressional Research Service’s guide to the legislative process and the IRS Newsroom for reliable updates.
What Should Taxpayers and Business Owners Do Before the Next Tax Season?
You don’t need to wait for Congress to act before preparing for tax season. Reviewing your current tax position and keeping records organized can help avoid last-minute surprises.
Review Your Income, Deductions, and Tax Credits
Check your income, paycheck withholding, filing status, and eligibility for deductions and credits. Business owners should review revenue, operating costs, payroll, and deductible expenses throughout the year.
Keep Personal and Business Financial Records Organized
Keep W-2s, 1099s, receipts, bank statements, payroll reports, and business expense records together. Businesses should reconcile accounts and maintain clear records of income, purchases, contractor payments, and employee compensation.
Revisit Estimated Tax Payments and Planned Business Expenses
If you receive income without sufficient withholding, check whether estimated payments are on track. Business owners should review planned equipment purchases and major expenses before committing. A potential deduction should be considered alongside the actual cost and business need.
Understand the Difference Between Federal and California Taxes
California does not automatically adopt every federal tax change. For example, it currently does not conform to the federal deductions for qualified tips and qualified overtime compensation. A worker may qualify for a federal deduction but still need to include the income when calculating California taxable income.
Here’s a quick comparison:
Tax provision | Federal treatment | California treatment |
Qualified tips deduction | Eligible workers may deduct up to $25,000, subject to requirements. | California does not currently conform to this federal deduction. |
Qualified overtime deduction | Eligible workers may deduct qualifying overtime premium, subject to limits. | California does not currently conform to this federal deduction. |
This difference matters when preparing both returns. A deduction claimed on a federal return should not automatically be carried over to the California return. Review the California Franchise Tax Board’s conformity guidance and its summary of federal tax law changes for current state treatment.
Don’t Make Financial Decisions Based on Proposed Tax Changes
A proposal is not an enacted law. Avoid changing investments, business structure, equipment purchases, or payroll practices solely because of political announcements. Check the rules currently in effect before making major decisions.
A Practical Tax Planning Timeline for Personal Taxpayers and Businesses
Planning stage | Personal taxpayers | Business owners |
Throughout the year | Track income, withholding, and household changes. | Record income, expenses, payroll, and transactions. |
Quarterly | Review estimated payments and withholding. | Check estimated taxes, cash flow, and bookkeeping. |
Before year-end | Review deductions, credits, and retirement contributions. | Evaluate investments, equipment purchases, and eligible expenses. |
Before filing | Organize W-2s, 1099s, receipts, and tax documents. | Prepare financial statements, payroll records, and expense reports. |
After filing | Review your return and adjust withholding if needed. | Review results and plan for the next year. |
Regular reviews help taxpayers respond to actual changes rather than reacting to every political announcement.
How Prado’s Professional Tax Preparation Can Help You Stay Ahead of Tax Changes
Keeping up with tax rules can be challenging, particularly when federal and California requirements differ. Professional tax preparation can help you understand filing obligations, identify eligible tax benefits, and reduce avoidable errors.
Make the Most of Available Personal Tax Deductions and Credits
Eligibility for deductions and credits can depend on income, filing status, and family circumstances. Professional personal tax preparation services can help review your records, identify potential tax benefits, and prepare your return using the applicable rules.
Keep Business Income, Expenses, and Payroll Records Accurate
Tracking revenue, operating expenses, payroll, and contractor payments supports accurate tax reporting. Professional business tax preparation services can help review financial information, identify potentially deductible expenses, and prepare required returns.
Understand Tax Filing Requirements for Your Business Structure
LLCs, S-Corps, and C-Corps have different tax and reporting requirements. Professional support can help owners understand how their entity is treated for tax purposes and whether their current structure remains appropriate.
Manage Federal and California Tax Filing Requirements
Federal tax treatment does not always match California rules. A tax professional familiar with both systems can help identify differences, prepare required returns, and explain how state conformity rules may affect taxable income.
Conclusion: Your Taxes May Not Change Today, But Planning Ahead Still Matters
The 2026 midterm results have changed the balance of power in Congress and could bring new debates over personal income taxes, deductions, credits, and business tax policies. But existing federal tax rules remain in effect until legislation is enacted, and California may treat some federal provisions differently. Personal taxpayers should review their income, deductions, and credits, while business owners should keep accurate financial records and understand how current rules apply to their business structure.
The most useful step right now is to stay informed, plan around the rules that currently apply, and review your tax position before making major financial decisions. If you need help preparing a personal or business return, explore www.pradotaxservices.com for support with your tax filing and planning needs.
Frequently Asked Questions About Trump's Midterm Defeat and Taxes
No, not immediately. The election may lead to new proposals, but the 2026 federal tax brackets remain in effect under current law. Any revisions must pass through the legislative process and become law.
Democrats can introduce legislation to revise or repeal provisions of the 2025 tax law. However, President Trump can veto legislation, and Senate rules may affect which proposals advance. Current provisions remain in place unless new legislation is enacted.
There is no automatic business tax increase because of the election. Corporate tax rates, depreciation rules, and business deductions remain governed by current law. Business owners should monitor proposals but should not assume an increase will take effect. Understanding how your business tax structure affects your tax obligations can also help you prepare for potential changes.
The credit could become part of future tax discussions, but current federal rules remain in place unless Congress changes them. For tax year 2026, eligible families may claim up to $2,200 per qualifying child, subject to income limits and other requirements.
Potentially, but California does not automatically adopt every federal tax change. For example, California currently does not conform to the federal deductions for qualified tips and overtime compensation.
You do not need to make immediate changes solely because of the election. Review income, deductions, credits, estimated tax payments, and business expenses under current rules. A tax professional can help assess your position and adjust your plan if new legislation is enacted.